Up land Revenue Code Provisions related to jurisdiction of courts, first appeal s/207 and second appeal s/208. Provision section 206 to section 217 states about the Jurisdiction
- Section 206 provides that notwithstanding anything contained in any law for the time being in force.
- The Clause Is stating that despite anything contains in any law for the time being in force means IT OVERRIDING, law in force.
- But subject to the provisions of this Code,
- No Civil Court shall entertain any suit,
- Application of proceeding to obtain a decision or
- Order on any matter
- Which the State Government, the Board,
- Any Revenue Court or
- Revenue Officer is, by or under this Code,
- empowered to determine, decide of dispose of.
- No Civil Court shall entertain any suit,
Means it expressly bar the Jurisdiction of civil court in Revenue matters.
Does Civil Courts have the jurisdiction to try Uttar Pradesh revenue matters?
Section 206 of up land Revenue Code expressly bar the Jurisdiction of civil Court in Revenue matter.
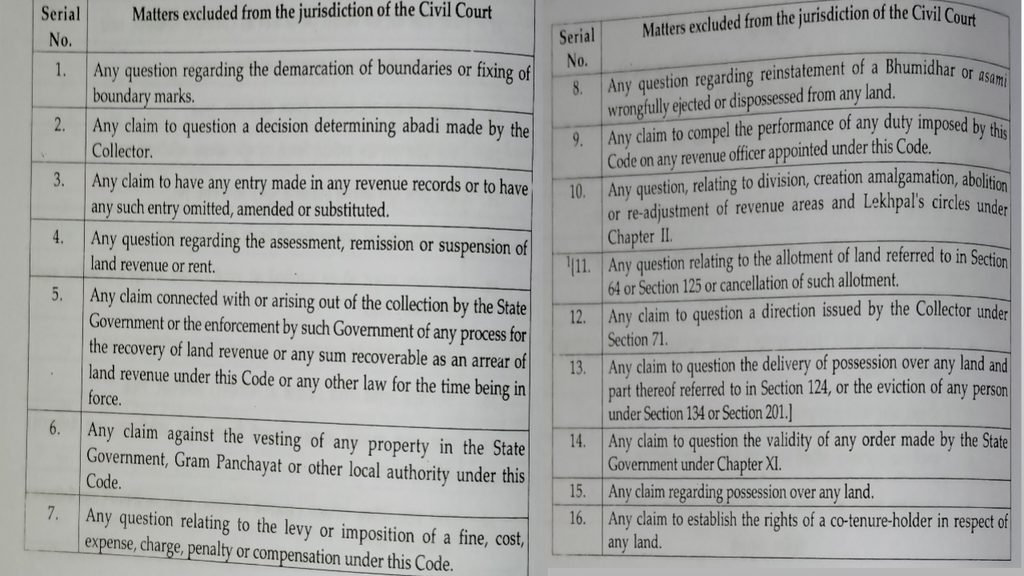
No Civil Court shall exercise jurisdiction over any of the matters specified in the Second Schedule.
- No Court other than the Revenue Court or the revenue officer specified,
- In Column 3 of the Third Schedule shall entertain any suit, application or proceeding specified in Column 2.
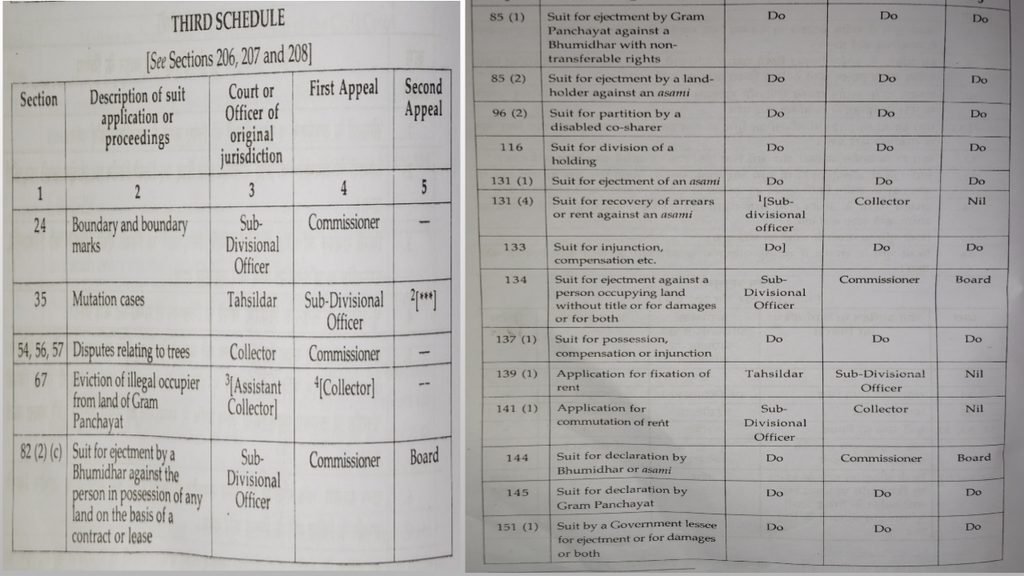
3rd schedule table of up Revenue Code 2006
| Section | Description of suit application or proceeding | court or officer of original jurisdiction | first appeal | second appeal |
| 1 | 2 | 3 | 4 | 5 |
| 24 | boundary and boundary mark | Sub Divisional officer | commissioner | |
| 35 | mutation cases | tahshildar | sub Divisional officer | |
| 54,56,57 | dispute relating to trees | Collector | commissioner | |
| 67 | Eviction of illegal occupiers from land of gram panchayat | assistant collector | collector | |
| 82(2)(c) | suit for ejectment by a Bhumidhar against the person in possession of any land on the basis of a contract or lease | Sub divisional officer | ||
| 85(1) | suit for ejectment by gram panchayat against a Bhumidhar with non transferable rights | |||
| 85(2) | suit for ejectment by a land holder against an asami | |||
| 96(2) | suits for partion by disabled co-sharer | |||
| 116 | suit for division of holding | |||
| 131(1) | suit for ejectment of an asami | |||
| 131(4) | suit for recovery of arrears or rent against an asami | Sub ddivisional officer | Collector | Nil |
| 133 | Suit for injunction compensation etc. | |||
| 134 | Suit ffor ejectment against a person occupying land without title or for damages or for both | Sub divisional officer | Commisioner | Board |
| 137(1) | Suit ffor possession, compensation or injection | |||
| 139(1) | application for fixation of rent | Tashildar | Sub ddivisional officer | Nil |
| 141(1) | application for commutation of rent | Sub divisional officer | Collector | Board |
| 144 | Suit for Declaration by asami | Commisioner | Board | |
| 145 | Suit ffor declaration by gram panchayat | |||
| 151(1) | Suit by a government lessee for ejectment or for damages or both |
Revenue court matter specified above comes under the exclusive jurisdiction.
No civil court shall exercise jurisdiction unless authorised by the UP land Revenue Code, 2006.
Dispute regarding Jurisdiction up land Revenue Code
- Up land Revenue Code Section 206(3) provides that any jurisdictional dispute with respect to any suit, application or proceeding.
- Shall not be entertained by any appellate, revisional or executing Court,
- Unless the objection was taken before the Court or officer of the first instance, at the earliest opportunity.
- And in all cases where issues are settled at or before such settlement, and unless there has been a consequent failure of justice.
Applicability of CPC 1908 and Limitation act 1983 up land Revenue Code
- Up land Revenue Code Section 214 further provides that unless otherwise expressly provided by or under this Code.
- The provisions of the Code of Civil Procedure, 1908 and the Limitation Act, 1963 shall apply to every suit, application or proceedings under this Code.
First appeal against final order of Tahsildhar or SDM, Up land Revenue Code
Section 207 provides that any party aggrieved by a final order or decree passed in any suit, application or proceeding specified in Column 2 of the Third Schedule.
May prefer a first appeal to the Court or officer specified against it in Column 4. Where such order or decree was passed by a Court or officer specified against it in Column 3.
Limitation period of first appeal against final order passed SDM or Tahsildhar
The period of limitation for filing a first appeal under section shall be thirty days from the date of the order of decree appealed against.
The appeal shall also lie against an order of the nature specifies in code of civil procedure 1908,
- Section 47 of the Code of Civil Procedure, 1908
- Attachment of share in movables( prohibiting transfer of share).
- In Section 104 CPC
- order from which appeal lies
- Order 43, Rule 1 of the First Schedule to the said Code.
- order 43 – appeal from orders,
- Rule 1 of first schedule- who may be joined as Plaintiffs.
Second appeal against Revenue matter final order up land Revenue
- Section 208 provides that where in any suit, application or proceeding specified in Column 2 of the Third Schedule.
- Any final order or decree is passed in any fen appeal filed under section 207, and any party to such appeal is aggrieved by it.
- Such party may prefer a second appeal to the Court specified against it in Column 5.
- Th Appellate Court shall not entertain a second appeal unless it is satisfied that the came involves a substantial question of law.
Limitation period against second appeal in up land Revenue Code
The period of limitation for filing a second appeal under section 208 up land Revenue Code, shall be ninety days from the date of the order or decree appealed against.
Grounds of Revision and Review under the Up land Revenue Code 2006
- Section 210 of up land Revenue Code provides that the Board or the Commissioner may call for the record of any suit or proceeding.
- Decided by any subordinate Revenue Court in which no appeal lies.
- For the purpose of satisfying itself or himself as to the legality of propriety of any order passed in such suit or proceeding.
Board or commissioner power to call for record in up land Revenue Code
- (a) if subordinates court appears to have exercised a jurisdiction not vested in it by law, or
- (b) failed to exercise a jurisdiction of vested. or
- (c) acted in the exercise of such jurisdiction illegally or with material irregularity.
- The Board, or the Commissioner, as the case may be, may pass such order in the case as it or he thinks fit.
Board’s power of review up land Revenue Code
Section 211 of up land Revenue Code provides that the Board may, of its own motion or on the application of any party interested.
Review any order passed by itself and pass such orders in reference thereto as it thinks fit.
- Grounds of review under section 211 of up land Revenue Code 2006
- No order shall be reviewed under sub-section (1), except on the following grounds:-
- (a) discovery of any new and important matter or evidence.
- (b) some mistake or error apparent on the face of record,
- (c) Any other sufficient reason.
- No order shall be reviewed under sub-section (1), except on the following grounds:-
- Note:-Orders passed on review shall not be reviewed.
Orders not be invalid on account of irregularity in procedure s/215 up land Revenue Code
- No order shall be reversed merely of any error, omission or irregularity in summons, notice, proclamation, warrant, order passed by Revenue officers.
- Unless such error, omission or irregularity has in fact occasioned a failure of justice.